The Blueprint: How Ordinary People Become Millionaires in 10 Years or Less
"Millionaire in 10 years" is a phrase that shows up in countless headlines, courses, and social media captions, often attached to a promise of a specific system that guarantees results. It's important to say clearly, upfront: no article, program, or strategy can guarantee that you will become a millionaire in 10 years, or at all. Income, market conditions, health, family circumstances, and plain luck all play a role, and outcomes vary enormously from person to person.
Published September 19, 2026
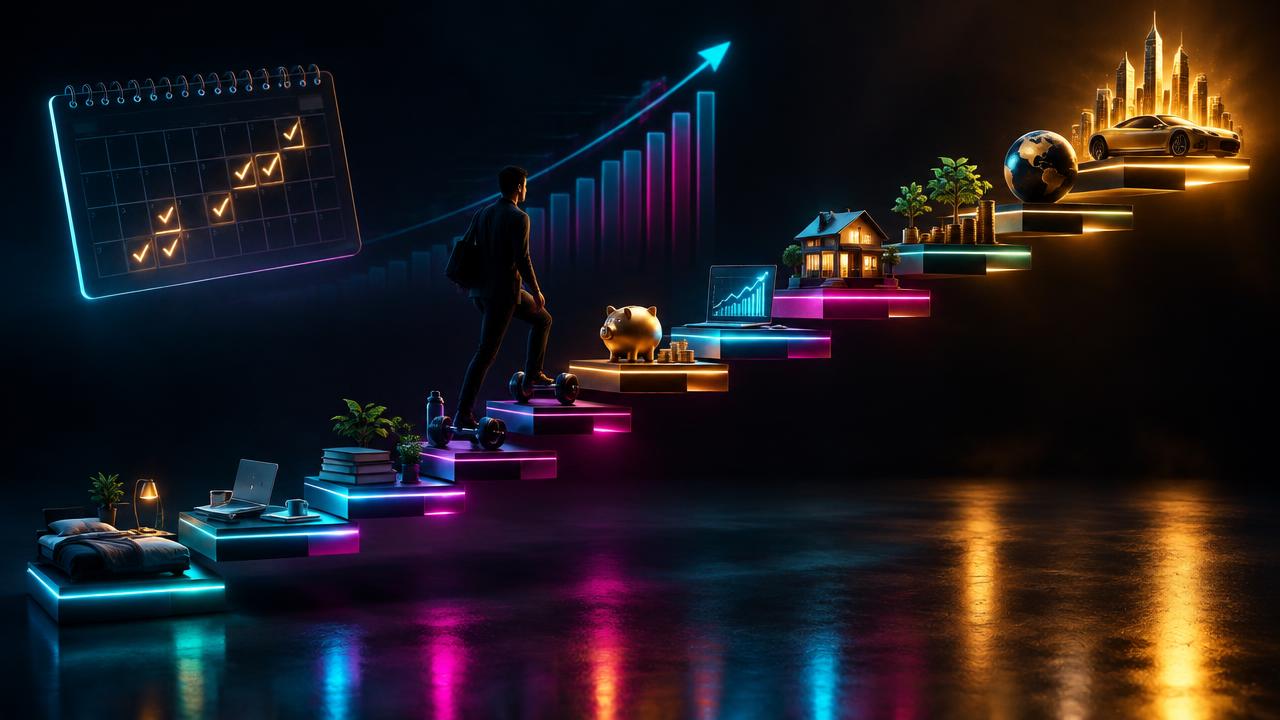
Introduction
"Millionaire in 10 years" is a phrase that shows up in countless headlines, courses, and social media captions, often attached to a promise of a specific system that guarantees results. It's important to say clearly, upfront: no article, program, or strategy can guarantee that you will become a millionaire in 10 years, or at all. Income, market conditions, health, family circumstances, and plain luck all play a role, and outcomes vary enormously from person to person.
What this article can do is walk through the realistic math and documented habits that show up repeatedly among people who have built million-dollar net worths over roughly a decade — not as a promise, but as an educational look at the mechanics involved. Understanding the math and the habits doesn't guarantee the outcome, but it does clarify what's actually required, which is often very different from what gets marketed.
The Math Behind a Million Dollars in a Decade
Before habits or mindset, it helps to understand the arithmetic, because it reframes the goal from "get rich" to "hit a specific number through specific inputs."
Working Backward From $1,000,000
To reach roughly $1,000,000 in 10 years through saving and investing alone (setting aside home equity or business value), someone would need to consistently invest a substantial amount each month, assuming a historical average market return, and let compounding do the rest. For context, using a simplified model with an assumed average annual return, investing several thousand dollars per month consistently over 10 years can approach that range — but actual results depend entirely on market performance, which is never guaranteed and can vary widely, including extended periods of low or negative returns.
Why Most "10-Year Millionaires" Aren't Purely Investing Their Way There
In practice, most people who reach a seven-figure net worth within about a decade combine multiple levers: rising income (often through career changes or entrepreneurship), business equity, real estate appreciation, and investment growth — rather than relying on a single savings account or index fund contribution alone. This matters because it means the realistic "blueprint" isn't one strategy, it's a combination of factors that compound together.
The Role of Starting Point
Someone starting with existing savings, no debt, dual income, or family financial support has a materially different math problem than someone starting with student debt and a single income. This isn't discussed enough in "blueprint" content, and it's a key reason identical strategies produce different timelines for different people.
The Core Levers People Actually Use
1. Increasing Income Faster Than Inflation
Cutting expenses has a ceiling — you can't cut below zero. Income, by contrast, has historically had a much higher ceiling for most people. Career moves, skill development, negotiating raises, and switching employers for pay increases are frequently cited as bigger accelerants to net worth growth than budgeting alone, especially in the first several years.
2. Maintaining a High Savings and Investment Rate
Regardless of income level, the percentage of income that's saved and invested rather than spent is one of the most consistently discussed factors in personal finance research. A higher savings rate shortens the time needed to reach any given net worth target, all else equal, because it increases both the amount invested and the amount of time that money has to grow.
3. Investing Consistently Through Market Cycles
Rather than trying to time the market, many long-term wealth builders invest on a fixed schedule regardless of market conditions, a strategy often referred to as dollar-cost averaging. This approach doesn't eliminate risk or guarantee returns, but it removes the pressure of trying to predict short-term market movements.
4. Building or Buying an Income-Producing Asset
Many self-made seven-figure net worths include a business, rental property, or other income-producing asset in addition to public market investments. These assets can accelerate net worth growth but also carry higher risk, more complexity, and more potential for loss than diversified public investments.
5. Avoiding Lifestyle Inflation
As income rises, a common pattern among those who build wealth relatively quickly is keeping spending increases modest relative to income increases, redirecting the difference toward savings and investments instead of proportionally upgrading their lifestyle.
6. Protecting Progress With Insurance and Emergency Savings
An emergency fund and appropriate insurance coverage are frequently cited as protective factors, because a single uninsured setback — a medical event, job loss, or major repair — can undo years of consistent saving if there's no buffer in place.
A Realistic 10-Year Framework (Educational, Not a Guarantee)
The following is a general, educational framework — not a personalized plan — for how people commonly structure this kind of long-term goal. Actual results will vary based on income, market performance, and individual circumstances.
Years 1–2: Foundation
Common focus areas include paying down high-interest debt, building a starter emergency fund, and establishing a consistent investing habit, even if the dollar amounts are small at first.
Years 3–5: Acceleration
This period is often when income growth (through career advancement, a side business, or additional education) starts to meaningfully increase the amount available to invest, alongside continued consistent contributions.
Years 6–8: Compounding and Diversification
By this stage, existing investments have had time to grow, and many people begin diversifying into additional assets such as real estate or a small business, if appropriate for their situation and risk tolerance.
Years 9–10: Reassessment
Net worth is reviewed against the original goal, with adjustments made based on actual market performance, career changes, and life circumstances, since the original 10-year estimate was always a projection, not a certainty.
Common Mistakes That Derail the Timeline
Chasing high-risk, high-hype investments in an attempt to accelerate results, which can just as easily set progress back significantly.
Underestimating taxes and fees, which can meaningfully affect net investment returns over a decade.
Stopping contributions during market downturns, which removes the benefit of buying at lower prices and can disrupt long-term compounding.
Comparing progress to curated social media timelines rather than realistic, individual circumstances.
Treating debt payoff and investing as mutually exclusive, when in many cases a balanced approach is more sustainable than an all-or-nothing strategy.
Why "10 Years" Is a Framework, Not a Promise
It bears repeating: some people reach a million-dollar net worth in less than 10 years, some take considerably longer, and some — due to income constraints, health issues, economic downturns, or other factors outside their control — may not reach that specific number at all despite consistent effort. The 10-year figure is a commonly discussed planning horizon in personal finance content, not a guaranteed outcome or a reflection of effort or worth. Readers should treat any specific timeline, including the one referenced in this article's title, as illustrative rather than predictive.
This article is intended for general educational purposes only and does not constitute personalized financial, tax, or investment advice. Individual circumstances vary significantly, and readers should consider speaking with a licensed financial professional before making significant financial decisions.
Conclusion
The idea of becoming a millionaire in 10 years is appealing precisely because it sounds achievable but bold — and for some people, under the right combination of income, market conditions, and consistent habits, it has been achievable. But there is no universal blueprint that guarantees this outcome for everyone who follows it. What the data and common patterns do suggest is that income growth, a high and consistent savings rate, disciplined long-term investing, and protection against setbacks are the recurring ingredients in most real-world examples. Understanding these mechanics is a useful starting point for anyone setting long-term financial goals, as long as it's paired with realistic expectations about risk, timelines, and individual circumstances.
Questions, answered
Frequently Asked Questions
Can anyone realistically become a millionaire in 10 years?
It's possible for some people depending on income, expenses, savings rate, market performance, and starting circumstances, but it is not a guaranteed or universal outcome. Timelines vary significantly from person to person.
What's the biggest factor in building wealth quickly?
Most documented examples point to a combination of a high savings/investment rate and rising income, rather than any single trick or investment type. No single factor works in isolation.
Is investing in the stock market enough to become a millionaire in a decade?
It depends heavily on the amount invested, consistency, and market performance, which is never guaranteed. Many people who reach seven-figure net worths in shorter timeframes combine investing with income growth, business ownership, or real estate.
What if I don't reach a million dollars in 10 years?
That's a common and normal outcome. Building wealth is generally a long-term, non-linear process, and a 10-year framework is a planning tool, not a deadline or measure of failure.
Does this article recommend specific investments or strategies for my situation?
No. This content is educational and general in nature and does not account for your personal financial situation. Consider consulting a licensed financial advisor for guidance tailored to your circumstances.
Keep exploring